Robotics Center · Annual Report Series
China · The 2026 Annual Report
State of Robotics 2026: China
Hardware, data, and foundation models — how China's supply chain density, state-backed industrial policy, and EV-adjacent manufacturing base have made it the world's humanoid production capital.
- Published
- March 2026
- Edition
- China
- Format
- Free · Web & PDF
Contents
Inside this report
From factory of the world to factory of the humanoid
In 2025, Chinese companies shipped roughly 80% of the world's humanoid robots. In 2026, that share is projected to rise as Unitree and AgiBot alone target 75,000+ unit annual capacity — more than the entire Western supply combined.
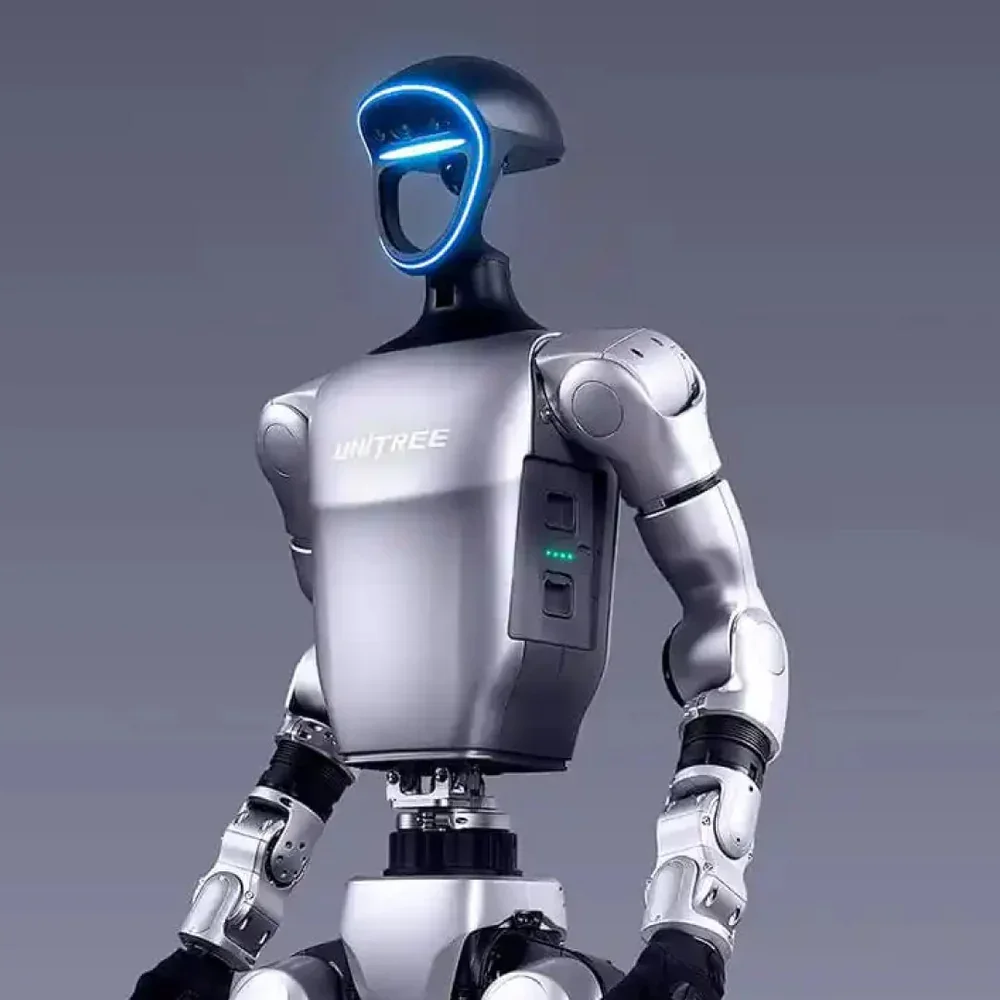
The Chinese robotics market reached $14.2B in 2026, up 47% year-over-year — the fastest growth of any major economy. Unit shipments tell an even starker story: Shanghai's AgiBot led the world with 5,168 humanoid units in 2025 (39% global share per Omdia), followed by Hangzhou's Unitree at 5,500 (Unitree's own figure disputes Omdia's second-place ranking). Combined with UBTECH (7% share) and Leju (~5%), Chinese firms control nearly 90% of global humanoid installations.
Three forces define China's position. First, supply chain integration: the Yangtze River Delta hosts the world's most vertically integrated humanoid supply chain — Unitree manufactures motors, reducers, and sensors in-house; component suppliers (DJI, DeepSeek, EV actuator makers) are within 2-hour logistics radius. Second, national policy coordination: the 2025 Humanoid Robot Action Plan, issued by MIIT and five ministries, targets 100,000 deployed humanoids by 2027. Third, demand-side scale: BYD (world's largest EV maker), CATL (dominant battery manufacturer), and Foxconn alone represent demand for tens of thousands of systems.
A prototype that takes 12 weeks to produce in the US or Germany is turned around in 10–14 days in Shenzhen, at a fraction of the cost. The same EV component supply chain that made China the world's largest car manufacturer now serves humanoids — actuators, gears, precision motors can often be repurposed directly between the two.
The China Market
Manufacturing scale, supply-chain vertical integration, and national industrial policy — the gravitational center of global robotics production.
Market size and trajectory
The China robotics market reached $14.2B in 2026, growing +47% year-over-year. This trajectory reflects the confluence of labor-market dynamics, policy incentives, and foundation-model-enabled deployment velocity discussed throughout this report.
Shipment landscape
Unit shipments tell a more revealing story than market dollars. Below, Robotics Center’s view of the 2025 competitive landscape for humanoid and leading-category robotics in China, shown alongside relevant global comparisons where instructive.
National Champions
Every robotics market has its flagship firms — the companies whose trajectory shapes the country's narrative and around which an ecosystem of suppliers, talent, and capital clusters.
Deployment by Vertical
Where robots are actually working in China today — and where growth is accelerating fastest. Robotics Center’s estimates reflect operational stock, not cumulative installations.
| Vertical | Deployed Units (2025E) | YoY Growth | Leading Form Factor |
|---|---|---|---|
| EV / Automotive | 28,000 | +42% | Precision 6-DoF + humanoid |
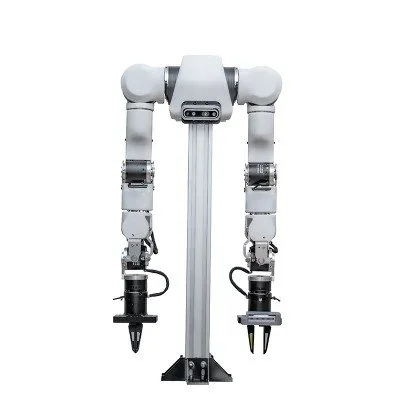
| Electronics (Foxconn etc.) | 19,500 | +35% | Bimanual arm system |
| Battery (CATL, BYD) | 12,500 | +51% | Precision arm + inspection |
| Logistics / JD, Cainiao | 8,200 | +39% | Mobile manipulator |
| General Manufacturing | 5,800 | +28% | Fixed industrial arm |
| Consumer / Retail demo | 3,400 | +124% | Humanoid (demo/PR) |
Strengths & Challenges
A candid assessment of what China does best in global robotics — and where structural vulnerabilities require attention.
Strengths
- Supply chain density — Yangtze River Delta hosts suppliers, robot makers, AI labs, and EV manufacturers within a 2-hour logistics radius. No equivalent cluster exists globally.
- Component cost advantage — China controls ~26% of global actuators, ~60% of rare-earths. Unitree manufactures motors and reducers in-house. The component bill of materials is structurally lower.
- Manufacturing velocity — 12-week Western prototype cycles compress to 10–14 days in Shenzhen. Iteration speed is the single largest moat in an industry where product-market fit is still forming.
- Policy coordination — Humanoid Robot Action Plan (2025) + 14th Five-Year Plan allocate capital, land, and procurement. Municipal programs (Beijing, Shanghai, Shenzhen) compete to host industry clusters.
Challenges
- Foundation model gap — Core VLA research remains US-originated. OpenVLA, Pi0, RDT-1B all emerge from North American labs. Chinese teams are fast-followers, not originators.
- Export market access — US policy scrutiny (CFIUS, Entity List) creates uncertainty for Chinese humanoid exports to the US and allied markets. Data handling concerns limit Western enterprise adoption.
- Brand trust abroad — Despite performance advantages, Western enterprise procurement cycles still favor Western-headquartered suppliers for mission-critical deployments. Reputation-building takes years.
- Software and standards — ROS 2 ecosystem contributions remain disproportionately Western. Chinese firms often integrate Western middleware rather than advance it, a long-term dependency.
Capital & Investment
The flow of venture capital, strategic corporate investment, and public funding that shapes robotics competitiveness in China.
In 2025, Chinese humanoid-related investment reached 39.8B RMB (~$5.5B) across 325 deals — 326% year-over-year growth. Unitree closed Series C at $3B valuation targeting $7B at IPO. Galbot raised over $300M. First twenty days of January 2026 saw 18 humanoid stocks with net inflows exceeding 100M RMB each. Capital availability is no longer the bottleneck; operational execution is.
Globally, investors increasingly cite proprietary data collection infrastructure as the primary defensibility argument in robotics. The question for China specifically: do its robotics companies generate deployment-specific data at a rate that compounds faster than foundation model improvements erode it? This is the question that 2026–2027 will answer.
What to Watch in 2027
Four themes Robotics Center’s research team believes will define China's robotics trajectory over the next 18 months.
01 · Unitree IPO resets valuations
A successful STAR market listing at $7B valuation would lift the entire Chinese robotics supply chain and likely trigger follow-on IPOs from AgiBot, XPENG Robotics, and Fourier.
02 · Export frictions intensify
Expect new US restrictions on Chinese humanoids in 2026–2027, mirroring semiconductor and EV playbooks. This accelerates rather than blocks domestic demand.
03 · Sub-$5K consumer humanoid
Unitree R1 at $5,900 is the opening salvo. 2027 likely sees sub-$5K consumer-grade humanoids from multiple Chinese firms — a price point that is categorically impossible for Western makers.
04 · Sovereign AI chips
Huawei Ascend and domestic inference accelerators will increasingly replace NVIDIA Jetson in Chinese humanoids. Performance gap is closing; supply is reliable.
China's robotics trajectory in 2026–2027 will be defined less by hardware breakthroughs than by whether the country can convert its distinctive advantages into repeatable deployment outcomes — at the speed that Chinese and US competitors are setting. The window for structural positioning is narrowing.